

Q3 Closed: Where Southeast Michigan Commercial Construction Stands Heading Into Q4 2026

Nine months into 2026, Southeast Michigan's commercial construction market enters the fourth quarter carrying real momentum in specific sectors and real discipline in cost planning across all of them. For owners and developers with a project targeting Q4 2026 or early 2027, here is a direct read on where things stand.
Demand Remains Sector-Specific, Not Broad-Based
The strongest activity this quarter has concentrated in industrial and data-center-driven construction, healthcare capital investment, and a tight, well-behaved retail sector. Office remains the softest major category, still working through elevated vacancy even as leasing activity shows early signs of stabilizing. Multi-family continues to be supported by structural demand that has not gone away. This is not a market where every sector is moving together. It is a market that rewards owners who understand which segment their project actually sits in.
Labor Costs Have Moderated, but Availability Has Not
Construction wage growth nationally has continued to cool from the sharper increases seen earlier in the recovery, which is a genuine change worth factoring into a 2027 budget. That said, moderating wage growth reflects a workforce that is fully committed to existing work, not one with new capacity opening up. Specialty trades, particularly electrical, mechanical, and structural crews, remain heavily booked into the active industrial and healthcare pipeline. Confirm current subcontractor availability directly rather than assuming it has loosened just because wage pressure has eased.
Material Costs and Tariff Exposure Remain a Moving Target
The tariff structure shifted meaningfully at the end of July, and material pricing, particularly for steel, copper, and aluminum, has continued to reflect that volatility through the quarter. Owners with a budget more than a few months old should have it refreshed against current pricing before using it for a financing decision. This has been true all year, and it remains true heading into Q4.
Financing Conditions Require a Realistic Baseline
The Federal Reserve held its benchmark rate through the summer with a notably cautious tone on inflation, which pushed out market expectations for near-term rate relief. Owners and developers sizing a 2027 pro forma around an assumed rate cut should treat that as an assumption to stress-test, not a given. Confirm the actual state of financing conditions at the time you are finalizing a capital stack, rather than working from an outdated assumption.
What This Means Heading Into Q4
The owners and developers who will have the smoothest path into 2027 are the ones treating the fourth quarter as the real planning window, not a holding pattern before January. That means confirming trade availability now, refreshing cost assumptions against current material pricing, and having an honest conversation about financing conditions as they actually stand, not as they were forecast to be earlier in the year.
Premier Construction and Design is available for those conversations now. If you have a project in Southeast Michigan targeting Q4 2026 or any part of 2027, reach out to our team directly.

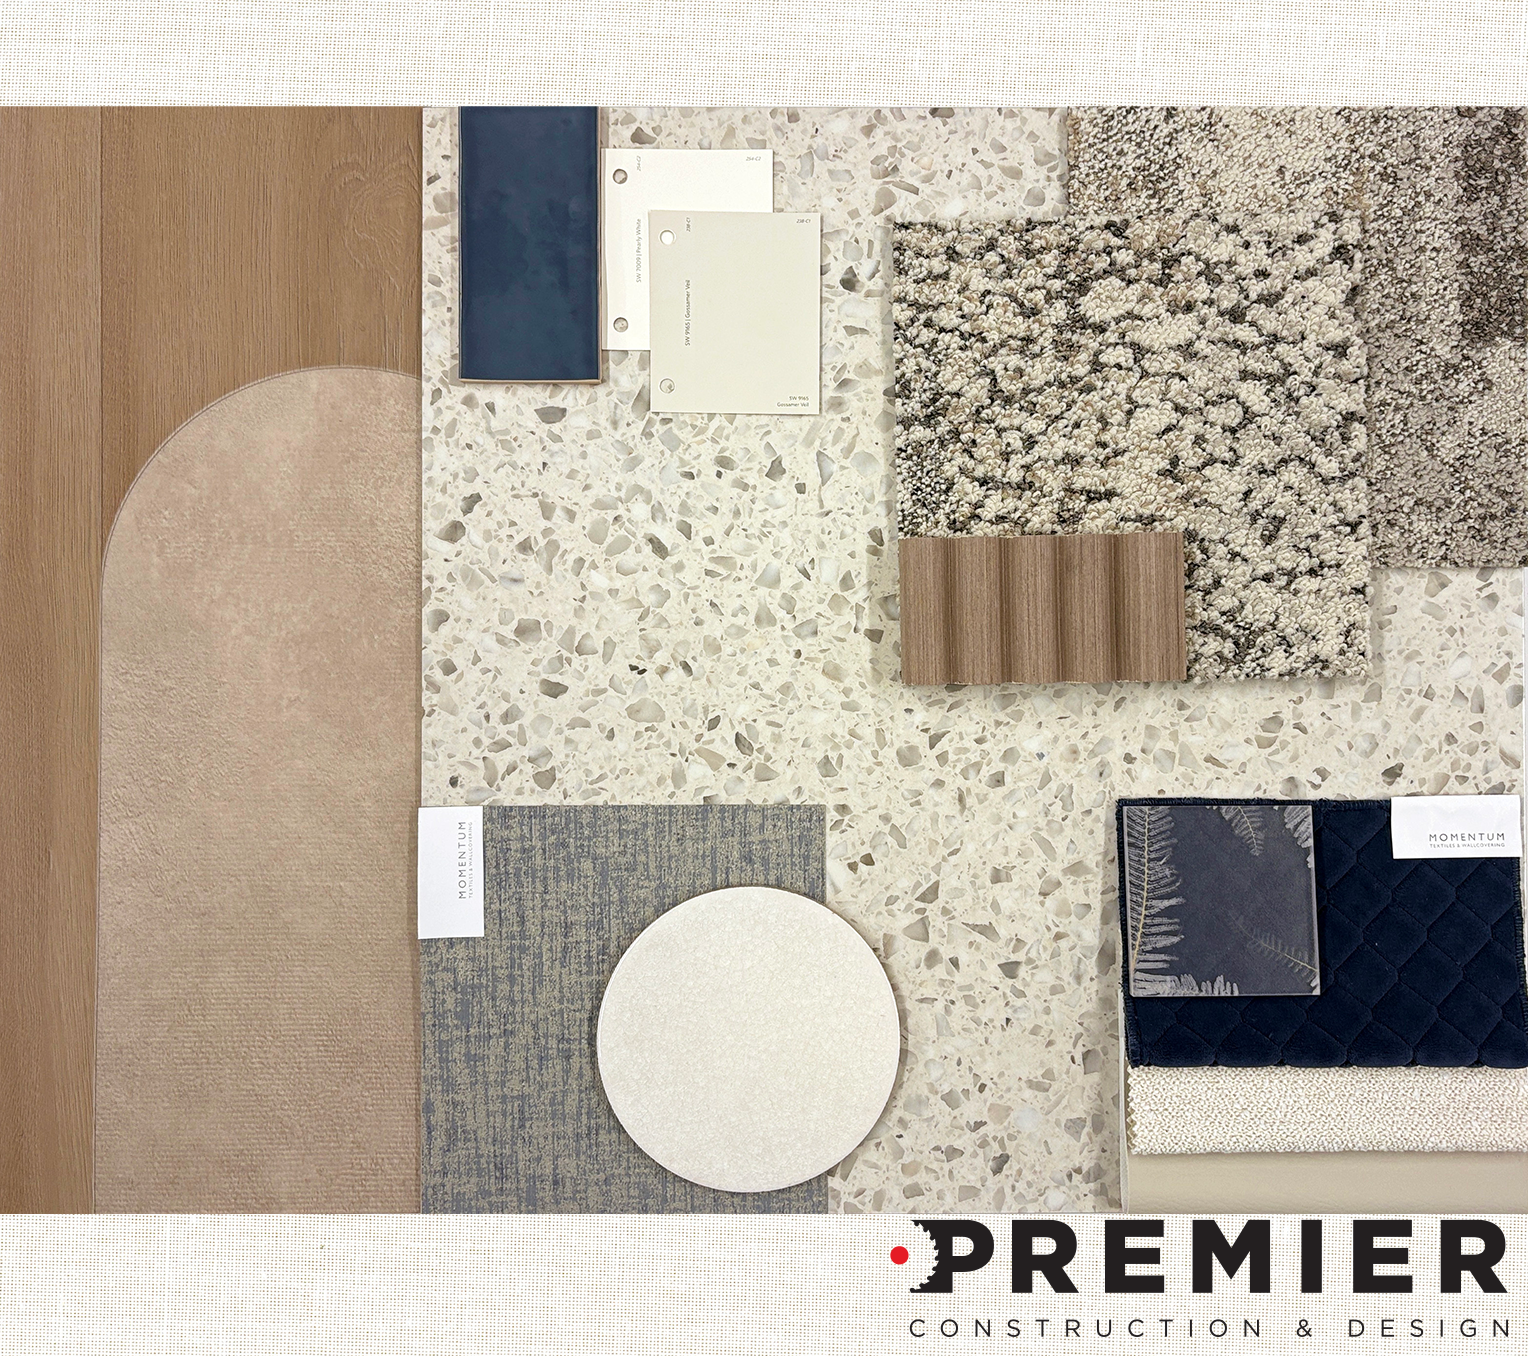
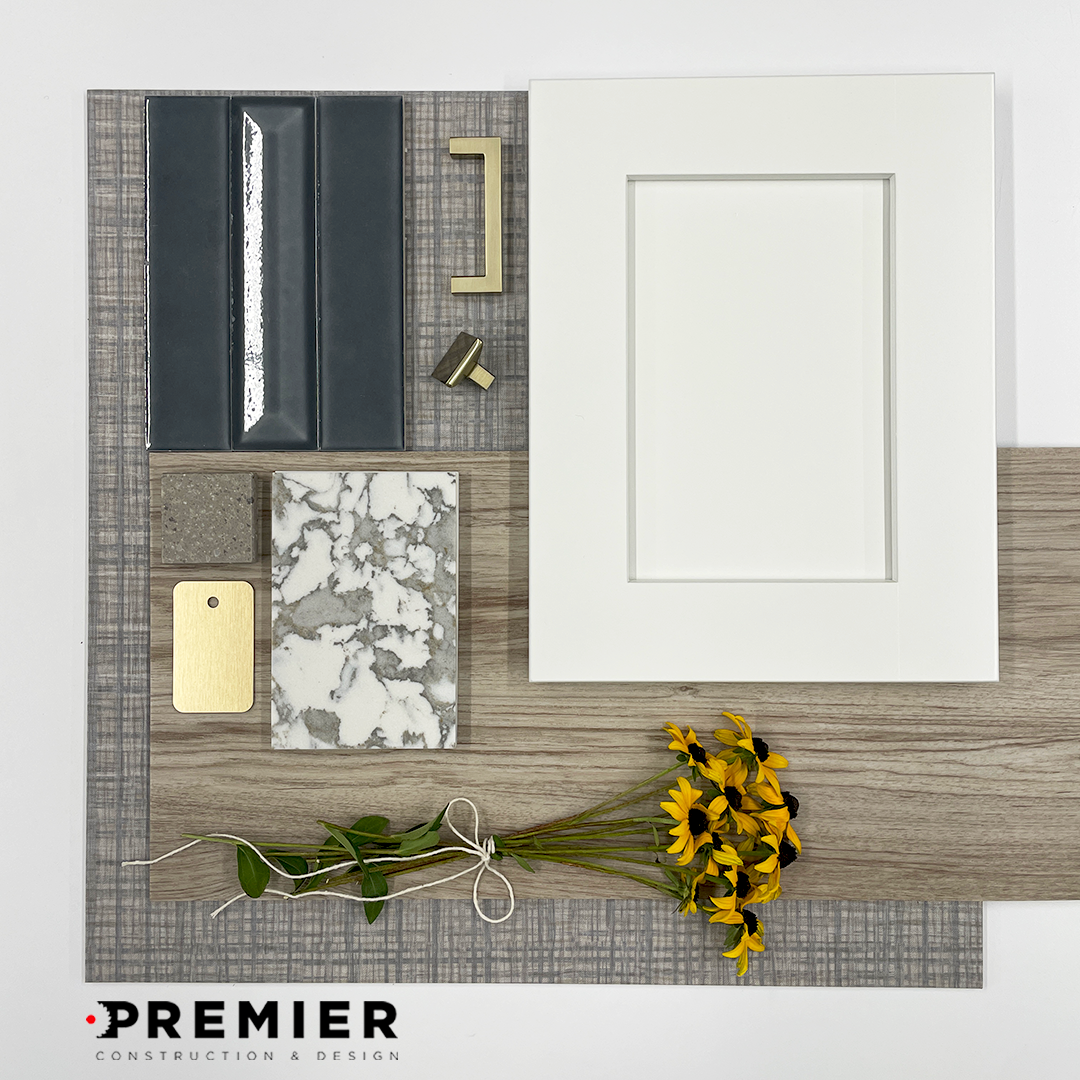
This muted palette blends soft blues and golds with clean white and natural wood grains. It’s perfect for creating interiors that evoke calm and comfort as the weather cools into autumn.

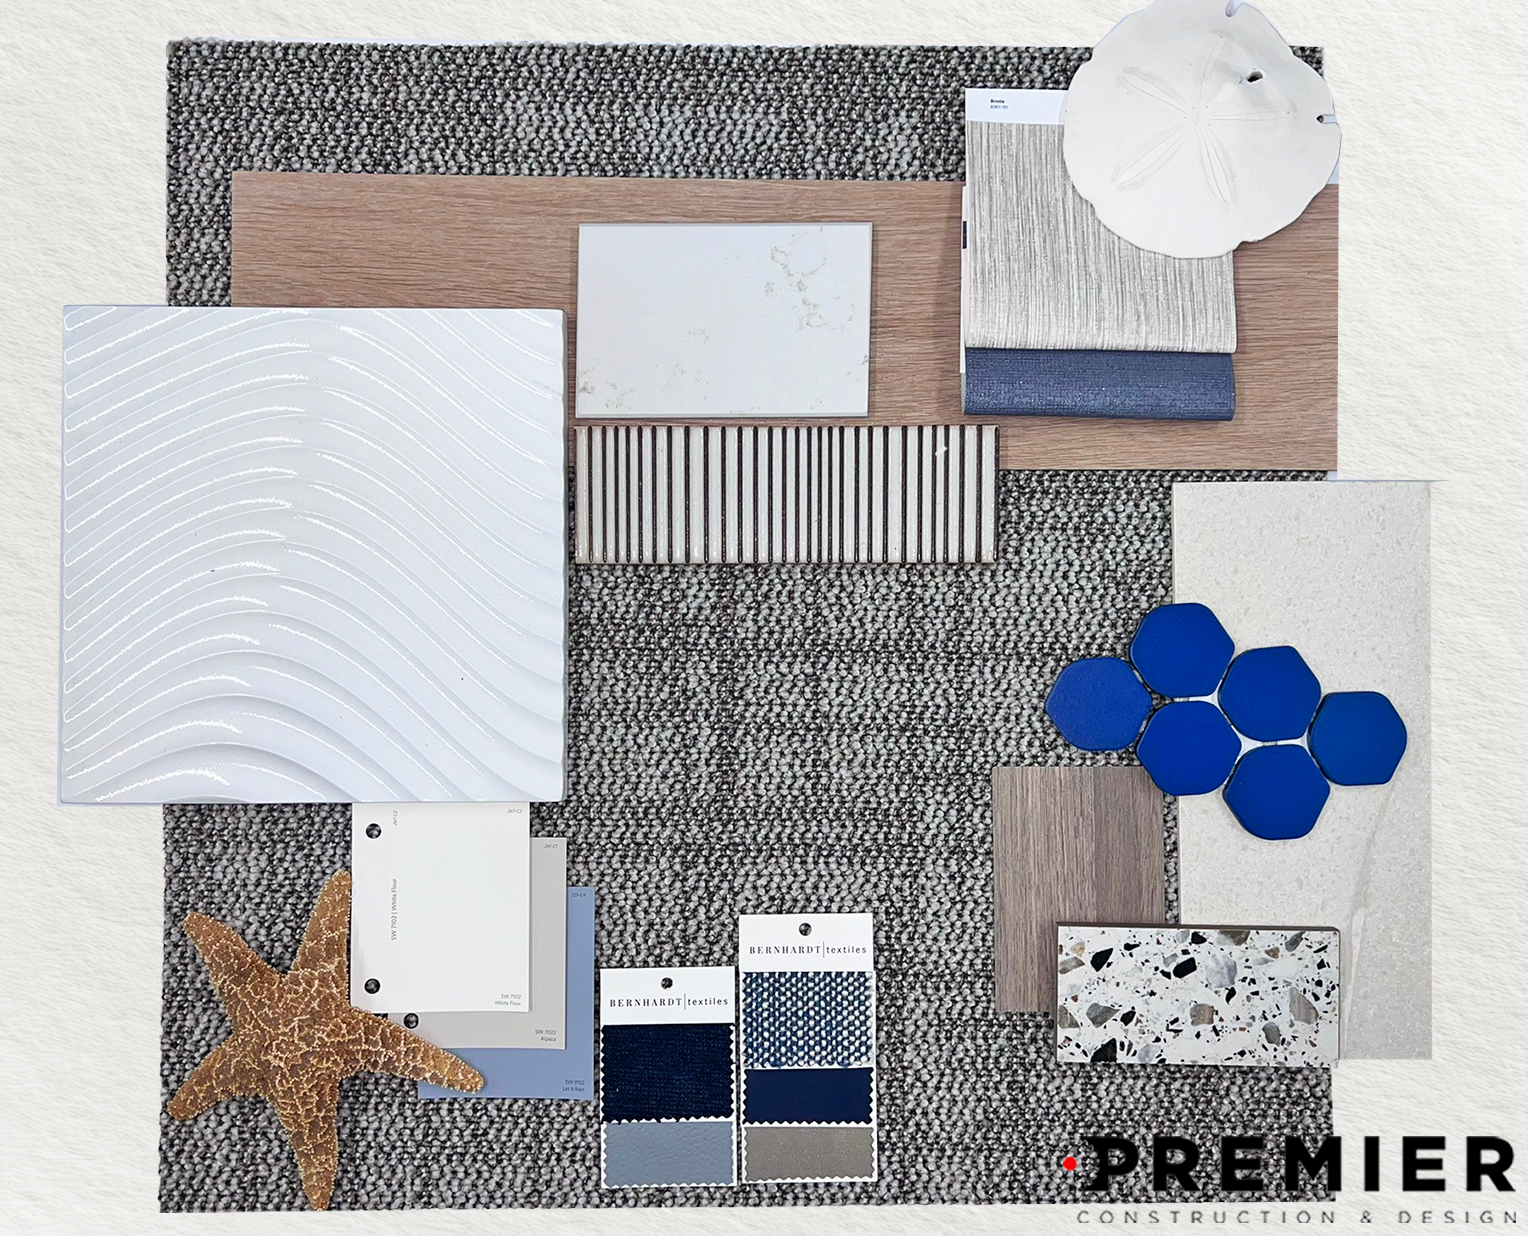
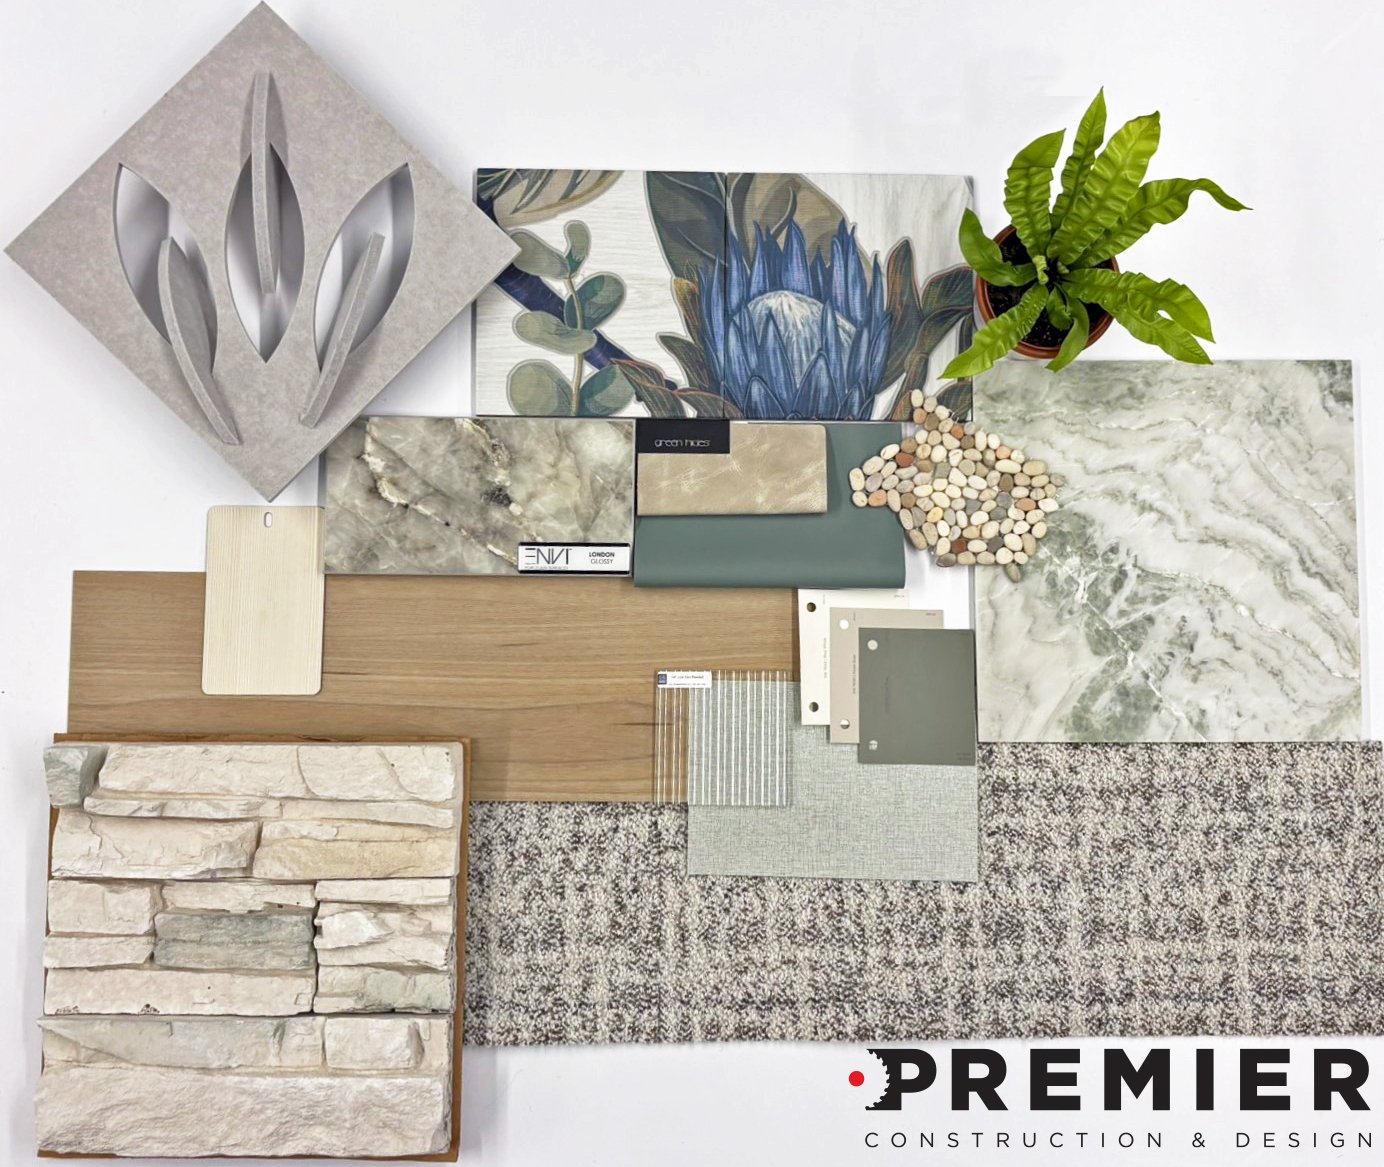
Sailing into summer with a relaxing feel. A combination of organic shapes, cool tone hues, and engaging textures can help to create a pleasant and tranquil ambiance.


Embracing everything spring has to offer. From subtle greens and light wood tones to playful textures and patterns. We're ready for the spring season!

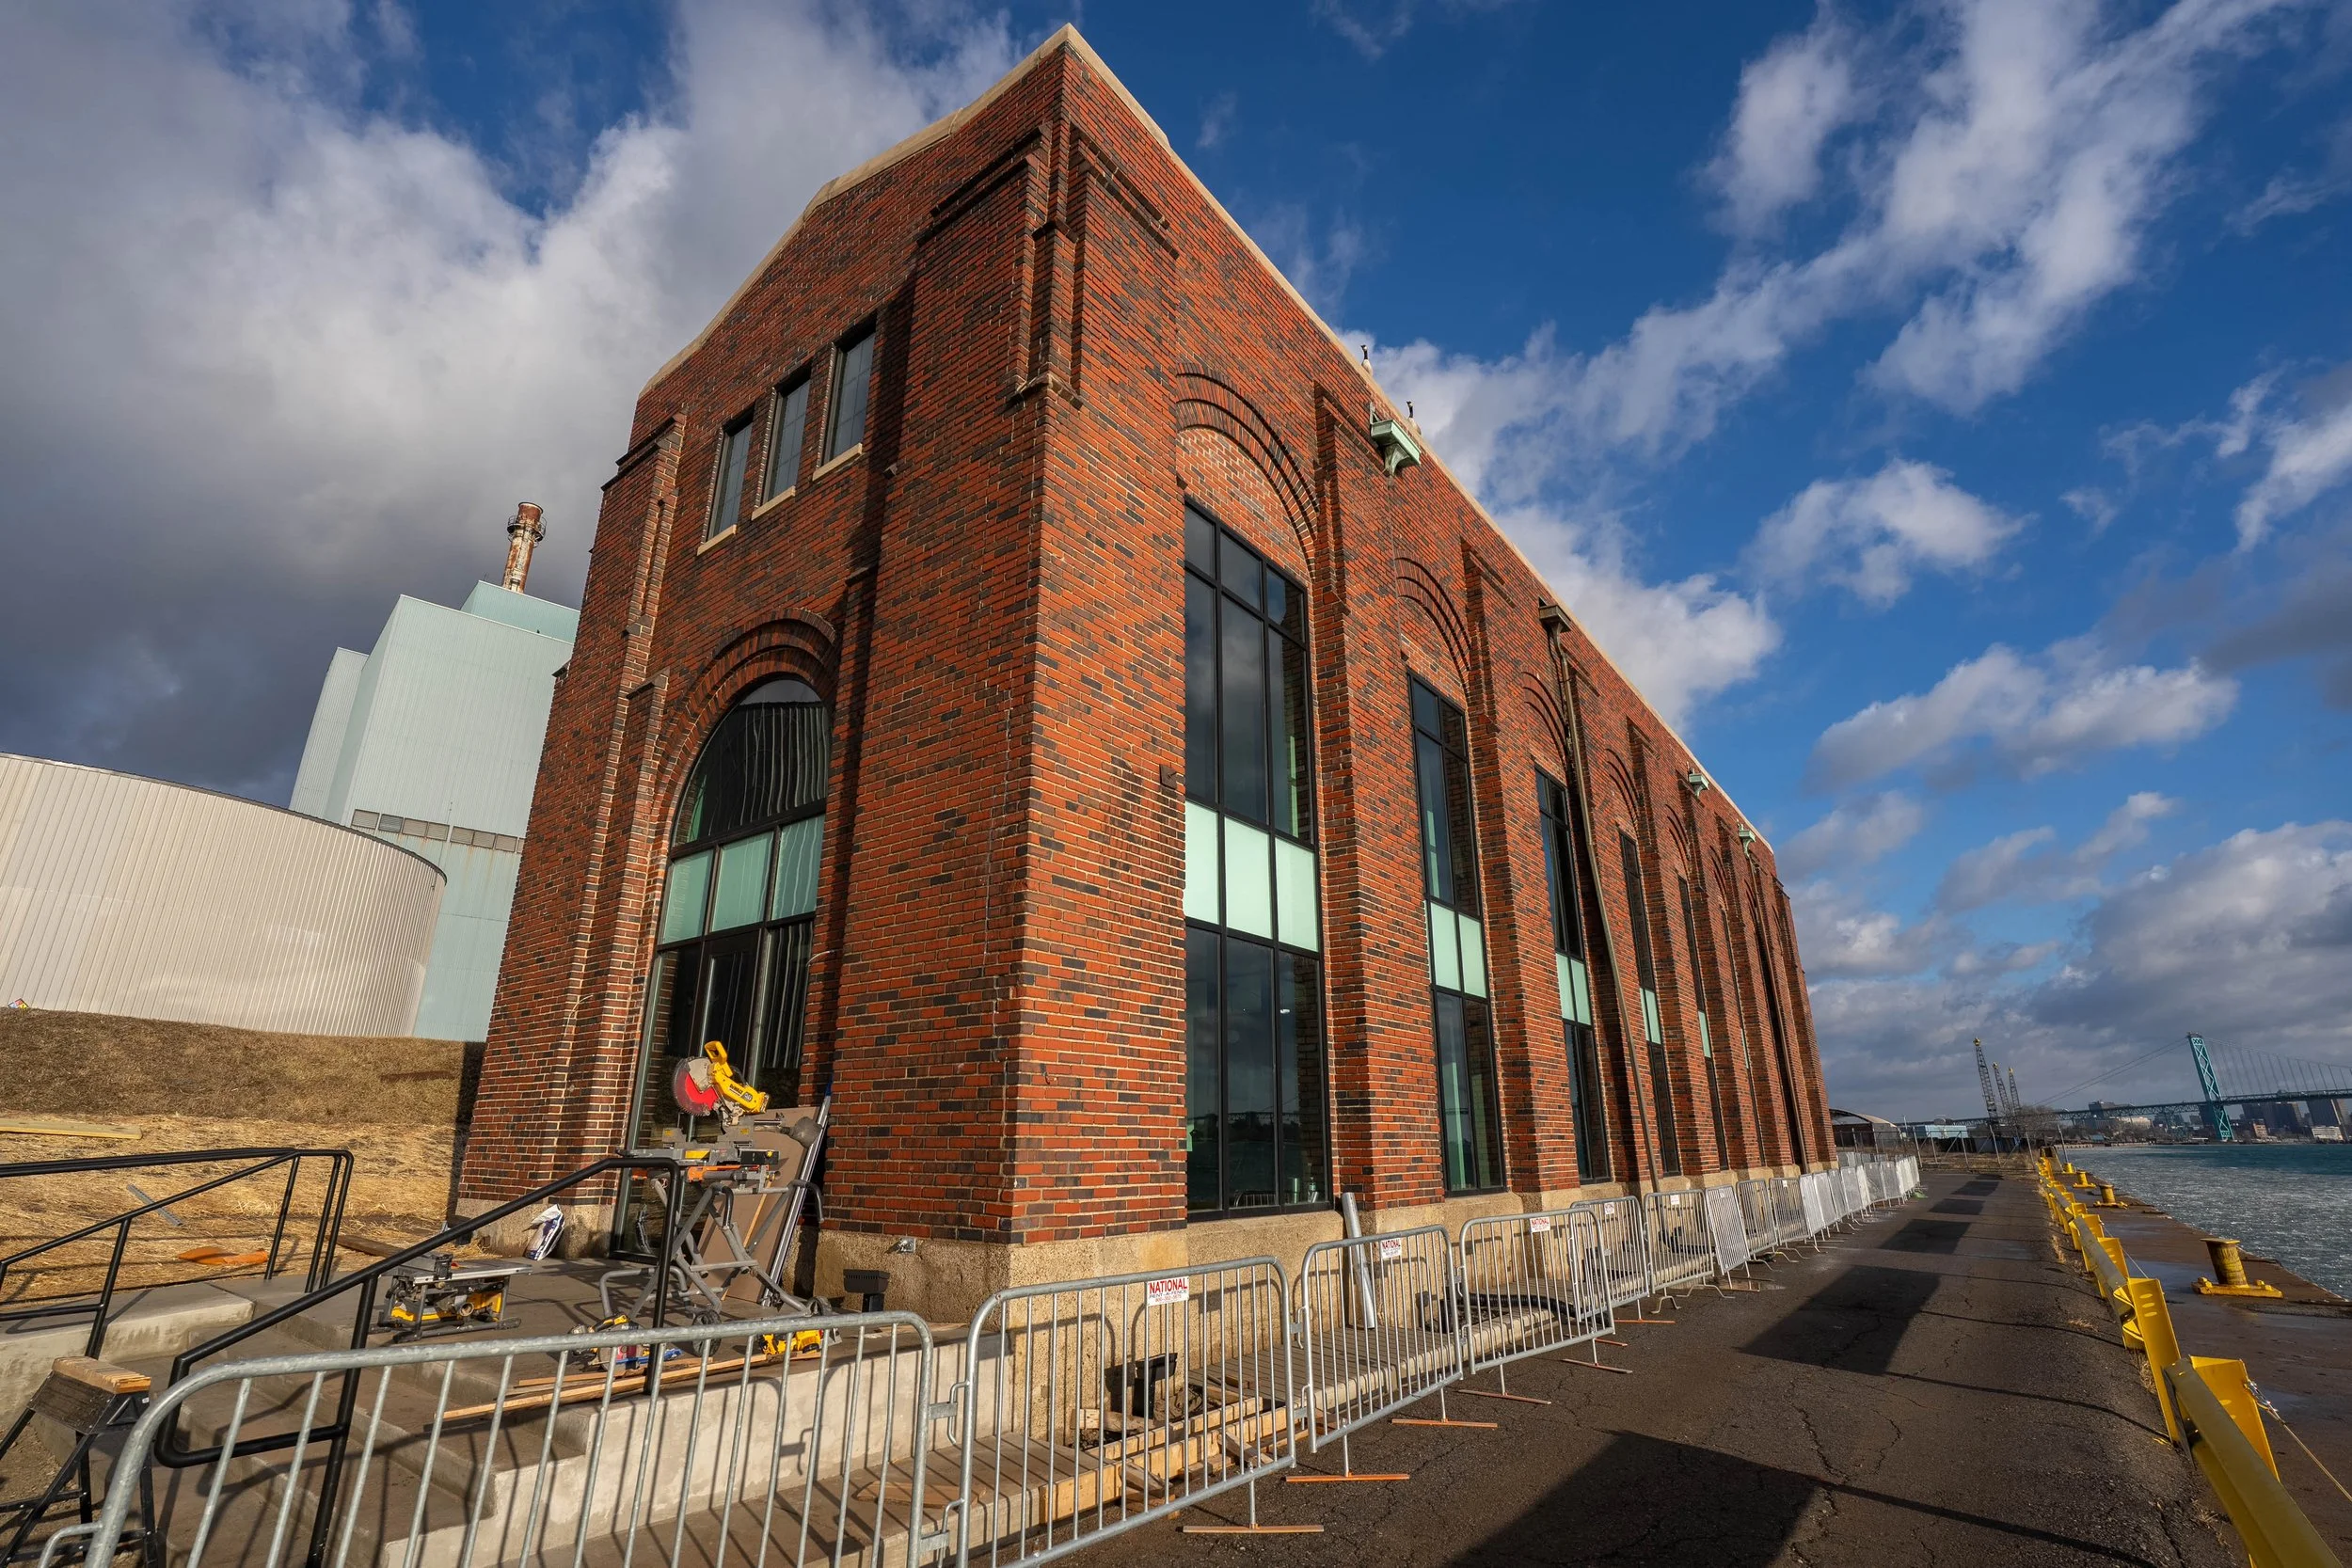
Premier Construction & Design is pleased to showcase our recent project in Corktown, Detroit, a testament to our commitment to realizing our clients' visions. This undertaking involved more than just construction; it was about integrating Design + Build processes and collaborating closely with the owners to create a unique entertainment destination that embodies the vibrant spirit of this revitalized neighborhood.

Sustainability continues to be a driving force in modern office design, with companies prioritizing eco-friendly materials, energy-efficient solutions, and biophilic elements to create healthier, more efficient work environments. By adopting these trends, businesses can reduce their carbon footprint while fostering employee well-being and productivity.

As we celebrate the New Year, we wanted to share some of the exciting projects from 2024 as we look forward to the projects we have slated for 2025!

As businesses that are focused on all things cutting edge and innovative, tech companies have often been seen as trendsetters in the world of office design. Offices for companies like Google and Facebook have been credited for driving demand for things like open plan layouts, casual atmospheres, and fun amenities like game rooms. But, as is the case for businesses in many other industries, tech companies can have some unique challenges to deal with when it comes to design.

Our January Palette of the Month ushers in the new year with a burst of energy and creativity. This vibrant collection combines bold textures, dynamic colors, and eye-catching patterns to create spaces that are both playful and sophisticated.

It’s hard to believe that 2025 is already just around the corner! Instead of looking back at the past year, we wanted to take a moment to look at what’s ahead. We’re already seeing signs of what some of the key office design trends will be in the new year. If you’re planning an office update in the near future, here are some trends you might want to keep in mind.

Glass walls are a very popular office feature for many good reasons. If you want to create space definition and add a sense of privacy without making the office feel too closed off, glass walls are a very effective way to do just that. Glass walls also help maximize access to natural lighting, can help keep noise levels under control, and can look very stylish. But if you’re interested in having glass walls in your office, there are a few different types to consider.

Our December Palette of the Month embodies excitement and sparkle as we embrace the holiday spirit. Enjoy this warmhearted palette as we prepare for the winter months!

Our November Palette of the Month evokes seasonal emotions and celebrates traditional autumnal hues with delightful, rich textiles and classic materials.

When you’re in the process of planning an office renovation, one important feature to think about is the flooring for your new space.
